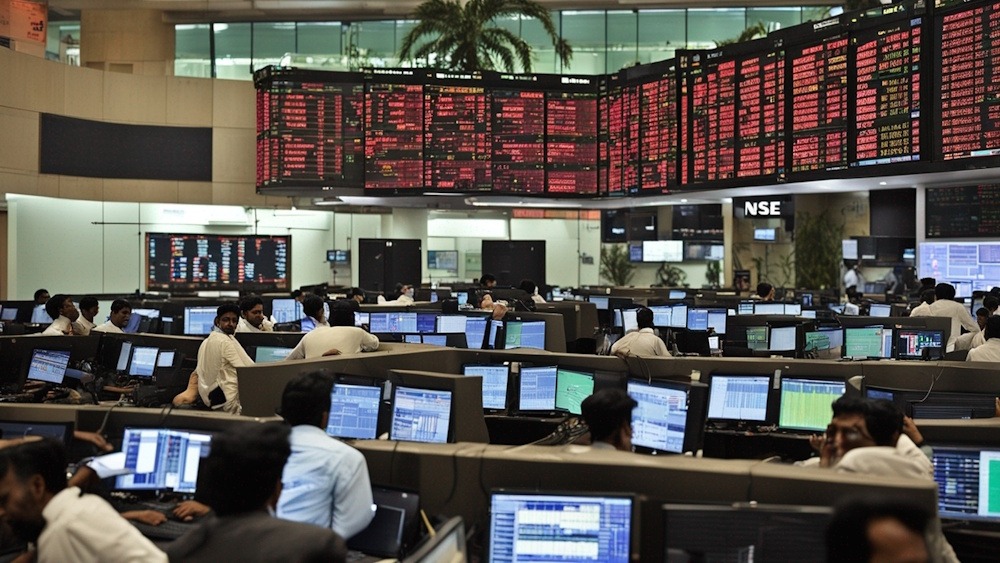
SGX Nifty October 2026 futures declined by 21.50 points, indicating a bearish start for the Nifty 50.
The Securities and Exchange Board of India has revised the closing auction session framework, introducing an auction window from 3:30 p.m. to 3:40 p.m. and altering the reference price calculation to the volume-weighted average price of trades executed during the final 15 minutes of continuous cash-market trading. Most changes will take effect from 7 December 2026. Order entry will conclude at a system-determined time that varies randomly between 3:38 p.m. and 3:40 p.m., allowing only limit and market orders during the auction phase. Index derivatives will be available for trading until 3:45 p.m., with the exception of expiring index contracts that will conclude trading at 3:30 p.m. on expiry days. In contrast, stock derivatives will continue to trade until 3:45 p.m. each day.
The cash-market post-close session is scheduled to operate from 3:50 p.m. to 4 p.m., during which trades will be executed at the closing price. SEBI has delineated fallback reference prices applicable in instances where no trades transpire in the final 15 minutes or on the day, and has elucidated the calculations for expiry settlement along with the limitations imposed on iceberg and stop-loss orders during CAS. Meanwhile, the government has increased the windfall tax on petrol exports and decreased levies on diesel, as per a notification released late Thursday nite. The tax on petrol export was increased to Rs 2.5 per litre from Rs 0.5 per litre, as stated in the notification. Conversely, the duty on diesel exports has been reduced to Rs 8.5 per litre from Rs 16 per litre, effective October 16, according to the order.
Institutional Flows:
Foreign portfolio investors sold shares valued at Rs 5,285.37 crore, whereas domestic institutional investors were net purchasers amounting to Rs 3,319.39 crore in the Indian equity market on 15 October 2026, as per provisional data. Foreign Portfolio Investors divested shares amounting to Rs 50,478.51 crore in October, up to the 15th of the month in 2026. This follows net selling of Rs 45,536.89 crore in September 2026, while FPIs were net buyers of Rs 17,366 crore in August 2026.
Global Markets:
Asian indices experienced gains on Friday as investors evaluated the rebound on Wall Street while balancing ongoing inflation concerns with the recent sell-off in technology stocks. Brent crude prices declined to approximately $105.40 per barrel following a rise above $106 in the prior session, as investors kept a close watch on developments in the Middle East and the global oil supply outlook. US equities experienced an uptick on Thursday. The Dow Jones Industrial Average increased by 1.08%, the S&P 500 saw an uptick of 0.33%, and the Nasdaq Composite experienced a rise of 0.08%. The rebound occurred as Treasury yields softened, prompting investors to gravitate toward defensive sectors, notably healthcare and consumer-related stocks.
The gains followed a technology-led sell-off earlier in the week, triggered by hotter-than-expected US consumer inflation data that revived concerns about further Federal Reserve interest rate increases. Technology shares continued to exhibit vulnerability as concerns arose regarding the extent to which robust demand for artificial intelligence would validate significant investments in data centers, semiconductors, and cloud infrastructure, especially within the context of elevated interest rates. Inflation continued to be a significant issue as US producer prices increased beyond expectations in September.
The Producer Price Index for final demand experienced a month-on-month increase of 1.3%, representing the most significant monthly rise since March 2022. Annual producer inflation accelerated to 6.3% from 5.6% in August, indicating that price pressures were broadening beyond energy. The producer inflation data came on the heels of a consumer price report that exceeded expectations, released on Wednesday. Together, the reports amplified worries regarding ongoing inflation and heightened uncertainty surrounding the Federal Reserve’s interest rate trajectory.
Domestic Market:
The key equity benchmarks experienced a rally on Thursday, driven by a decline in US Treasury yields and a decrease in crude oil prices, which collectively enhanced investor sentiment. The Sensex surged over 1,500 points, while the Nifty briefly reclaimed the 23,000 mark. The unwinding of global AI and semiconductor stocks has also bolstered Indian IT shares, as evidenced by the Nifty IT index’s approximately 11% increase over five sessions. Reliance Industries experienced a significant increase following Jio Platforms’ announcement regarding its planned IPO, while major banking stocks saw gains in anticipation of their upcoming quarterly results.
The rally was bolstered by purchases in major stocks and anticipations regarding September-quarter earnings, despite global markets facing pressure from worries about AI-related debt and escalating competition within the semiconductor sector. The S&P BSE Sensex surged 1,533.72 points or 2.11% to 74,315.61. The Nifty 50 index experienced an increase of 374.65 points, reflecting a rise of 1.66%, reaching a level of 22,997.35. It reached the peak for the day at 23,056.40.